What is the scope of the Artificial Intelligence (AI) Fleet Optimization Market?
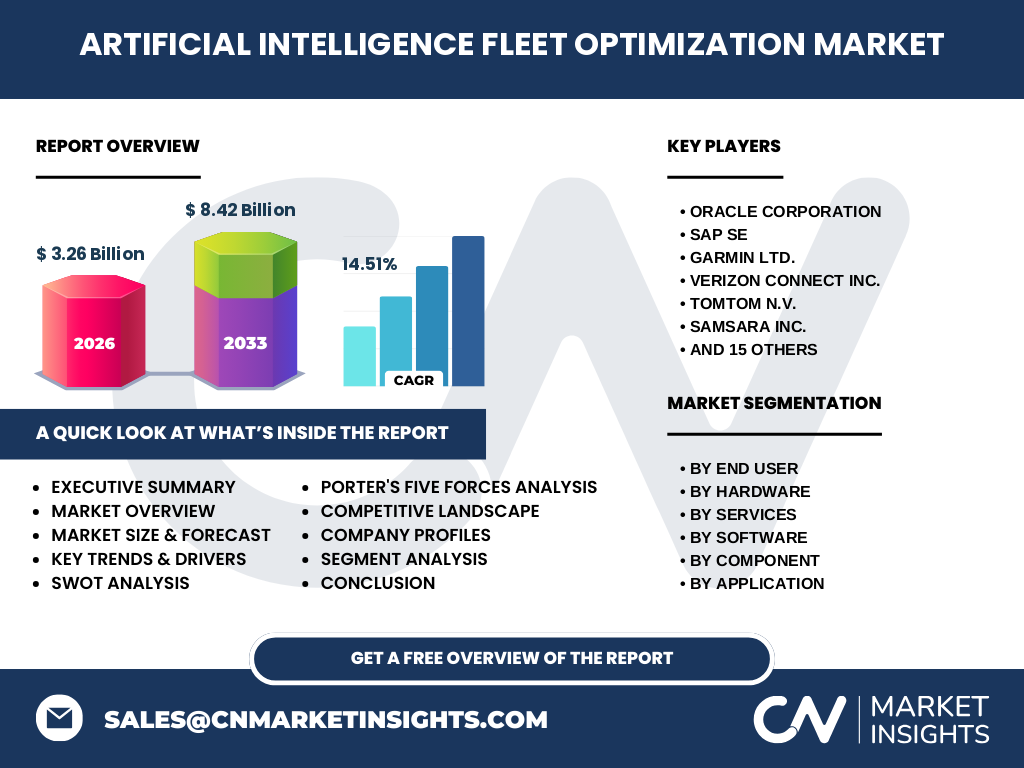
Our analysis indicates that the Artificial Intelligence (AI) Fleet Optimization Market stands at $3.26 Billion in 2026, establishing a critical baseline for operational intelligence. This sector encompasses advanced algorithmic routing, telematics, and predictive maintenance infrastructure deployed across commercial transport networks to drastically reduce fuel burn and wear on internal combustion engines as well as emerging electric fleets.
Key market drivers, restraints, challenges, and opportunities shaping Artificial Intelligence (AI) Fleet Optimization Market
Stringent emissions mandates from agencies like the EPA and EU force operators to adopt solutions that minimize idling and optimize paths. While high capital expenditures for Internet Of Things Sensors present a temporary restraint, the massive push toward electrification creates boundless opportunities for firms integrating real-time battery analytics.
Emerging trends and growth patterns in Artificial Intelligence (AI) Fleet Optimization Market
The transition toward edge-computing architectures dominates current deployment patterns, reducing latency for in-cab safety alerts. Fleet Complete and Platform Science are leading the charge by embedding applications directly into vehicle dashboards, transforming static trucks into connected mobile nodes generating continuous telemetry.
COVID-19 impact analysis — how the pandemic affected Artificial Intelligence (AI) Fleet Optimization Market and the recovery trajectory
Supply chain bottlenecks during the pandemic exposed deep vulnerabilities in legacy transport infrastructure, accelerating automated dispatch adoption. Operators quickly turned to cloud-based route optimization software to navigate volatile delivery windows, permanently shifting risk management toward resilient, algorithmic logistics.
Competitive landscape — major players, market concentration, and strategic dynamics
The ecosystem features a mix of telematics giants and agile software pure-plays like Samsara Inc. and Geotab Inc. Market concentration is moderately high, with established vendors aggressively acquiring niche predictive maintenance innovators to secure end-to-end proprietary hardware-software ecosystems.
Executive summary — high-level synthesis of key findings about Artificial Intelligence (AI) Fleet Optimization Market
Driven by compounding efficiencies, the Artificial Intelligence (AI) Fleet Optimization Market is poised to reach $8.42 Billion by 2033, expanding at a robust 14.51% CAGR. Organizations failing to integrate cloud-based analytics risk severe margin compression amid rising fuel volatility and stringent safety compliance.
Market forecast — projected growth from 2027 to 2033
Between 2027 and 2033, market expansion will accelerate dramatically as logistics firms replace reactive maintenance models with automated predictive upkeep. Our data suggests cumulative annual additions will consistently outpace traditional IT spending benchmarks across both large fleets and regional carriers.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Segmentation spans hardware, software, and services, with Route Optimization Software and Driver Monitoring Software driving core operational value. End-user categories range from Public Transport and Logistics And Transportation to Automotive Original Equipment Manufacturers, each prioritizing distinct safety and compliance telemetry metrics.
Regional market analysis — geographic distribution and performance across regions
North America dominates revenue generation due to early IoT sensor adoption and dense logistics corridors connecting major shipping hubs. Meanwhile, Asia-Pacific exhibits the fastest adoption velocity, spurred by massive state-backed investments in smart public transport networks and EV commercial fleets.
In-depth regional review — detailed examination of key regional markets
European operators face stringent carbon reporting directives, favoring fleet analytics software that accurately quantifies scope 1 emissions. In contrast, North American deployments concentrate on driver retention and mitigating hours-of-service violations through advanced telematics integration.
Company profiles — strategic positioning of leading companies in Artificial Intelligence (AI) Fleet Optimization Market
Industry stalwarts like Oracle Corporation and SAP SE leverage enterprise resource planning dominance to embed fleet tools into broader supply chains. Simultaneously, specialized innovators like Motive Technologies Inc. and Uptake Technologies Inc. focus on machine-learning-driven predictive maintenance to preempt catastrophic mechanical failures.
Porter's Five Forces analysis — competitive forces assessment
Supplier power remains moderate given standardized IoT hardware components, but buyer power is high as enterprise fleets demand highly customized integration services. The threat of new entrants is mitigated by the steep engineering hurdles required to build reliable, real-time routing neural networks.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Core strengths lie in substantial fuel savings and enhanced driver safety, while high upfront implementation costs remain a primary weakness. Significant opportunities emerge in autonomous vehicle dispatch management, whereas rising cybersecurity threats to connected vehicle networks represent an escalating external peril.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value flow originates with semiconductor and sensor raw material suppliers, moving through hardware manufacturers to software developers like TomTom N.V. and Descartes Systems Group Inc. Integrators then package these solutions for end-users operating massive freight or public transit networks.
Investment insights — strategic recommendations and high-potential areas
Venture capital and private equity should target startups specializing in hybrid edge-cloud architectures and predictive maintenance for electric commercial vehicles. Companies possessing proprietary driver behavior analytics algorithms present the highest probability of lucrative strategic acquisition.
Conclusion and key takeaways
Adopting artificial intelligence in fleet management is no longer optional for maintaining operational margins in competitive logistics ecosystems. Stakeholders must prioritize scalable, cloud-deployed architectures that adapt fluidly to evolving regulatory landscapes and alternative powertrain technologies.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by cross-referencing primary stakeholder interviews with C-level fleet executives, public customs trade registry data, and macroeconomic secondary indicators. This multi-layered approach ensures high fidelity in sizing niche software and hardware segments.
Scope of the report — coverage parameters and limitations
This report covers global deployment models across five core end-user verticals, evaluating hardware, software, services, and component tiers from 2026 through 2033. Excluded from this scope are purely military tactical combat vehicles and consumer-grade personal navigation devices without commercial fleet integration.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent market activity highlights aggressive partnerships, such as Powerfleet Inc. expanding its footprint through strategic acquisitions and Samsara Inc. launching generative-AI-powered coaching tools. These moves underscore a broader industry pivot toward proactive, automated driver safety interventions.